Powered by Unipro Tech
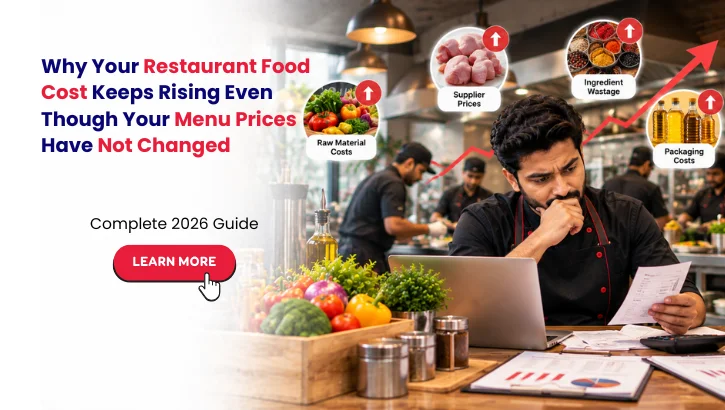
Why Your Restaurant Food Cost Keeps Rising Even Though Your Menu Prices Have Not Changed
A complete guide for Indian restaurant owners, QSR operators, and F&B chain managers who want to identify and stop food cost leakage permanently
The Number That Keeps Moving in the Wrong Direction
A Hyderabad restaurant owner pulled up his monthly P&L for August 2026. Revenue: Rs 14.2 lakh. A good month. Up from Rs 13.1 lakh the month before. His menu prices had not changed since March. His supplier costs had increased slightly on a few items but nothing dramatic. His kitchen team was the same. His covers were up.
His food cost percentage was 41.3%.
Six months ago it was 35.8%. A year ago it was 33.2%.
The gap between 33.2% and 41.3% on Rs 14.2 lakh of revenue is Rs 1.15 lakh every single month. That is money that was once profit and is now food cost. Nothing dramatic happened to create this gap. No single event. No supplier crisis. No category price explosion. Just a slow, steady drift upward in food cost percentage that nobody noticed clearly until the August accounts made it impossible to ignore.
This is the food cost creep problem. It is the most common hidden margin problem in Indian restaurants and it almost never has a single cause. It is always a combination of factors that individually seem small but together add up to a percentage point here, a percentage point there, until the cumulative drift is significant enough to turn a profitable restaurant into one that is working very hard for very little.
This guide identifies every specific cause of food cost creep, explains how to measure each one, and provides the operational fixes that stop the drift and bring food cost back to where it should be.
Section 1: What Food Cost Percentage Is and Why It Drifts Upward
Food cost percentage is the proportion of your restaurant’s revenue that is spent on the ingredients used to produce the food sold. If you spend Rs 35 on ingredients to produce a dish that sells for Rs 100, the food cost percentage for that dish is 35%. If your total monthly ingredient cost is Rs 4.5 lakh and your total monthly revenue is Rs 12 lakh, your overall food cost percentage is 37.5%.
Most Indian restaurant owners know their food cost percentage approximately. Very few know it precisely, and almost none know it at the dish level in real time. This is exactly why it drifts.
Why food cost percentage drifts upward over time:
Food cost percentage is not a fixed property of a menu. It is the dynamic result of dozens of decisions made every day in the kitchen: how much of each ingredient goes into each dish, how much is wasted in preparation, how much spoils before being used, what price the restaurant paid for each ingredient this week, and how accurately each dish matches the recipe standard.
Each of these factors moves independently and in its own direction. Ingredient prices change when suppliers adjust their rates or when seasonal availability affects commodity prices. Portion sizes drift when kitchen staff plate by feel rather than by weight. Wastage increases when over-preparation leaves excess mise en place at the end of each service. Procurement prices rise when the purchasing relationship with a supplier becomes less competitive over time.
None of these individual movements triggers an alarm. No single event is significant enough to notice on its own. But they accumulate month by month until the food cost percentage that was 33% has drifted to 41% and the restaurant owner is staring at accounts that do not make sense.
Section 2: The Eight Causes of Food Cost Creep in Indian Restaurants
2.1 Portion Sizes That Have Grown Without Anyone Deciding to Grow Them
Portion creep is the most universal and most underestimated cause of food cost drift in Indian restaurants. It works like this. A chef plates a dish by feel. Their natural tendency is to be generous because generous plating feels like good hospitality and generates positive customer feedback. Over weeks and months, the portion that was 180 grams becomes 200 grams becomes 220 grams. Nobody made a decision to increase the portion. It grew through the accumulated effect of individual plating decisions.
A 40-gram increase in the protein portion of a dish that costs Rs 260 per kg represents an additional cost of Rs 10.40 per plate. At 80 plates per day that is Rs 832 per day. At 300 service days per year that is Rs 2.5 lakh annually from one ingredient on one dish alone.
2.2 Recipe Standards That Exist in Memory Rather Than on Paper
Most Indian restaurant kitchens operate on recipes that exist in the head chef’s memory and in the informal knowledge of the kitchen team. When the head chef is present, the dishes come out consistently because they are being produced under direct supervision. When the head chef is absent, on their day off, during illness, or after they leave to join a competitor, consistency drops because the recipe standard was never documented at a level that allowed it to be replicated without the person who carried it in their memory.
Undocumented recipes create food cost variability because different kitchen team members interpret the same dish differently. One person’s “handful of cashews” is another person’s “generous handful”. The difference is food cost percentage.
2.3 Wastage That Is Not Being Recorded
Kitchen wastage in Indian restaurants falls into four categories: raw material spoilage before use, preparation over-production that goes unconsumed, cooking errors that result in unsalable output, and plate returns from the dining room. Every one of these categories represents ingredient cost with no corresponding revenue.
Most Indian restaurant kitchens manage wastage informally. Spoiled produce is discarded without being weighed or recorded. Over-prepared curry base is kept overnight and used the next day or discarded at close without a formal record. A burnt batch of bread is thrown away as an understood operational loss.
Without recording, wastage cannot be measured. Without measurement, it cannot be managed. The kitchen that was wasting 7% of its daily ingredient purchase in January is still wasting 7% in August with no awareness that this is happening or any mechanism to identify where the waste is occurring.
2.4 Supplier Prices That Have Risen Gradually
Ingredient prices in India move frequently and in multiple directions. Some commodities spike sharply with seasonal shortages and then normalise. Others drift gradually upward as input costs for suppliers increase, logistics costs change, or market dynamics shift.
The gradual price increases are the more dangerous ones for food cost management because they do not trigger action the way a sharp spike does. When tomatoes go from Rs 30 to Rs 80 per kg in two weeks, every restaurant owner notices and responds. When cooking oil rises from Rs 140 to Rs 165 per litre over eight months through a series of small increments, many restaurant owners absorb each small increase without formally re-evaluating the dishes that use cooking oil most heavily.
By the time the cumulative impact is visible in the monthly food cost percentage, the restaurant has been absorbing higher costs for months without the menu pricing or recipe adjustments that would have maintained the intended margin.
2.5 Menu Items Whose Recipes Were Never Accurately Costed
A significant number of dishes on Indian restaurant menus were added without a formal recipe costing exercise. The chef proposed a dish, it was tasted and approved, the price was set based on what seemed reasonable for the category and the competitive environment, and it went on the menu. The actual ingredient cost was never calculated precisely.
When the dish is a Puzzle, low volume and potentially high margin, this does not matter much. When it is a Star, high volume and consistently ordered, an uncalculated food cost can be a significant hidden drain. A dish that is priced at Rs 250 and ordered 100 times per week but has an actual ingredient cost that represents 48% of that price, not the 35% assumed when it was added, is costing the restaurant Rs 3,250 per week in unplanned margin loss.
2.6 Free Items and Staff Meals That Are Not Being Tracked
Most Indian restaurants offer complimentary items to certain customers, to long-standing regulars, or as a service recovery gesture. Most Indian restaurants also feed their kitchen and service staff one or two meals per day as part of the employment arrangement. Neither of these costs is wrong. Both of them represent ingredient cost that has no corresponding billing transaction.
When these costs are not tracked, they are invisible. The complimentary papad and raita given to every large table, the staff biryani prepared at lunch, the birthday dessert sent out for the table in the corner — each is a small amount but together they may represent 1 to 2% of total food cost with no revenue attached.
2.7 Receiving Shortfalls From Suppliers
Supplier deliveries that arrive with fewer units than invoiced, lower quality than specified, or with substituted products that cost the same but are less suitable for the restaurant’s recipes, represent a form of food cost inflation that most Indian restaurant kitchens absorb without formally identifying.
When receiving is done informally, without comparing the physical delivery against the purchase order, short deliveries are paid for at the full invoiced price. Lower-quality substitutions increase the waste percentage because the substituted product does not perform as expected in the recipe. Both outcomes inflate food cost without being visible as a specific cause.
2.8 Delivery Channel Economics Being Ignored in Food Cost Calculation
This is a post-2020 food cost issue that many Indian restaurant owners still have not fully integrated into their management approach. When a dish is sold through Zomato or Swiggy, the restaurant receives the order value minus the platform commission of 25 to 35%. The food cost percentage for that dish, calculated as ingredient cost divided by net revenue received rather than by the list price, is significantly higher than the same calculation on a dine-in order.
A dish with a 35% food cost at Rs 300 dine-in has a food cost percentage of 45.5% when the same dish is ordered through Zomato at Rs 300 and the restaurant receives Rs 216 after 28% commission. A restaurant where delivery accounts for 50% of orders and has not adjusted its food cost thinking for the delivery channel is managing food cost based on a blended calculation that understates the true delivery cost.
Section 3: How to Calculate Your True Food Cost Right Now
Most Indian restaurant owners calculate food cost by dividing total monthly ingredient purchases by total monthly revenue. This gives a workable approximation for overall food cost management but it has three specific limitations.
Limitation 1: It does not distinguish between food cost on dine-in orders and food cost on delivery orders where different revenue amounts apply to the same ingredient cost.
Limitation 2: It does not show food cost at the dish level, meaning you cannot identify which specific dishes are above or below your target food cost percentage.
Limitation 3: It mixes current period ingredient costs with any opening stock that was consumed from a previous period at a different price, creating a calculation that does not accurately reflect the current relationship between what you are buying and what you are selling.
The more accurate food cost calculation:
For each dish: (Total ingredient cost per serving at current purchase prices) divided by (Net revenue per serving after platform commission if applicable) multiplied by 100.
For the overall restaurant: (Total ingredient cost consumed in the period, not total purchased) divided by (Net revenue received from all channels after platform commission) multiplied by 100.
The difference between total ingredient purchased and total ingredient consumed matters because opening and closing stock changes in a given period mean purchases do not equal consumption. A restaurant that bought Rs 5 lakh of ingredients in August but started August with Rs 80,000 of stock and ended with Rs 60,000 consumed Rs 5.2 lakh, not Rs 5 lakh, in that period.
Section 4: The Recipe Discipline Problem: Where Most Indian Restaurants Lose the Most
Recipe discipline is the consistent application of documented, gram-specific recipe standards at every cooking session, by every kitchen team member, regardless of which chef is on duty.
It is the most impactful food cost control lever available to any restaurant and the one most commonly neglected in Indian restaurant operations.
What recipe discipline requires:
Every dish on the menu must have a documented recipe that specifies every ingredient with its exact quantity in grams or millilitres. Not “a handful of cashews” but “22 grams of cashews”. Not “a ladle of gravy” but “180 ml of gravy base”. Not “chicken as needed” but “160 grams of marinated chicken thigh”.
These gram-level specifications serve three functions simultaneously. They define the quality standard so that every customer receives the same dish regardless of which chef prepared it. They define the cost standard so that the food cost of every dish is predictable and controllable. And they provide the data needed for inventory management so that the restaurant knows exactly how much of each ingredient is needed for each day’s service.
How to build recipe discipline in an existing Indian restaurant kitchen:
Start with your five highest-volume dishes. For each one, cook the dish while weighing every ingredient. Document the exact quantities. Make this the reference standard. Train every kitchen team member on these five recipes using the weighted standards. Over the following weeks, extend this process to every dish on the menu.
The process takes time. The payoff is immediate. A restaurant that moves from approximate plating to gram-specific portion control on its five highest-volume dishes typically sees a 1 to 2 percentage point reduction in overall food cost percentage within the first month, simply from eliminating the portion creep that had accumulated on those dishes.
Section 5: The Wastage Problem: The Cost Nobody Is Measuring Accurately
Food wastage in Indian restaurants is almost universally underestimated because it is almost universally undermeasured. Restaurant owners know they have wastage. They do not know how much it costs in rupees because nobody is recording it systematically.
The four categories of restaurant wastage and how to measure each:
Raw material spoilage. Every ingredient discarded before use because it has spoiled, wilted, or passed its useful window must be weighed and recorded with a reason code before disposal. The daily total by ingredient category tells the kitchen management team which ingredients are being over-ordered, stored incorrectly, or rotated incorrectly.
Preparation over-production. When a kitchen prepares more mise en place than the service requires, the excess either carries to the next service or is discarded. Both outcomes have a cost. Recording how much of each prepared item went unused at the end of each service session is the first step to calibrating preparation quantities accurately.
Cooking errors. Burnt items, over-seasoned preparations, presentation errors, and other kitchen mistakes that result in unsalable food must be recorded against the specific dish and the specific session. Patterns in cooking errors reveal training needs and equipment issues that are not otherwise visible.
Plate returns. When a customer returns a dish, the restaurant loses both the food cost and the revenue for that plate. Recording plate returns with reason codes identifies dishes that are consistently returning, which may indicate a recipe, presentation, or expectation management issue.
The financial case for systematic wastage recording:
A restaurant recording 8% daily wastage on Rs 3 lakh monthly ingredient purchases is losing Rs 24,000 per month to wastage. Reducing this to 4% through systematic recording and targeted reduction saves Rs 12,000 per month, Rs 1.44 lakh annually, from a management practice that costs almost nothing to implement.
Section 6: The Procurement Problem: How Buying Without Data Inflates Food Cost
The procurement relationship between an Indian restaurant and its ingredient suppliers has a direct and significant impact on food cost percentage. Restaurants that manage their procurement actively and systematically consistently achieve lower ingredient costs than restaurants that maintain passive supplier relationships.
The specific procurement practices that control food cost:
Weekly price comparison for key commodities. For the ingredients that represent the largest share of your food cost, primarily proteins, cooking oil, and high-use spices, systematic weekly price comparison between suppliers creates the competitive pressure that keeps prices at market rate rather than drifting above it through relationship inertia.
Recipe-linked ordering quantities. When ordering quantities are calculated from the expected service volume and the recipe-specified ingredient quantities per cover, over-ordering is reduced to the minimum buffer needed for service reliability. When ordering is done by habit or by estimate, over-ordering is systematic and wastage from the excess is built into the operation.
Goods receipt verification. Every delivery must be physically checked against the purchase order before the delivery is accepted. Shortfalls must be noted and deducted from the payment. Quality variances must be flagged and resolved. A systematic receiving process that takes 15 additional minutes per delivery can save the equivalent of several percentage points of food cost over a year by eliminating the gradual supplier creep that accumulates when deliveries are accepted without verification.
Section 7: The Delivery Channel Problem: Why Zomato and Swiggy Make Food Cost Look Worse
The delivery channel food cost problem deserves specific, dedicated attention because it affects every Indian restaurant that generates meaningful delivery revenue and is still being managed by many restaurant owners as if it does not exist.
The mathematics of delivery channel food cost:
Scenario | Dine-In Order | Zomato Order (28% commission) |
Menu price | Rs 320 | Rs 320 |
Platform commission | Zero | Rs 89.60 |
Net revenue to restaurant | Rs 320 | Rs 230.40 |
Ingredient cost | Rs 108 | Rs 108 |
Food cost percentage | 33.75% | 46.9% |
The same dish, at the same price, with the same ingredient cost, has a food cost percentage of 33.75% on dine-in and 46.9% on Zomato after commission. If a restaurant is calculating its blended food cost percentage as ingredient cost divided by gross order value including platform orders at list price, it is systematically underestimating its true delivery channel food cost.
The four responses to delivery channel food cost:
Delivery-specific pricing. Some dishes can support a price premium on delivery platforms that accounts for the commission while keeping the dish competitive in the delivery market. This is not always possible but where it is, it is the cleanest solution.
Delivery menu curation. Removing dishes from the delivery menu whose food cost after commission is above a defined threshold concentrates delivery revenue on dishes that are actually profitable after the platform’s take rate.
Direct ordering channel development. Every order that comes through a direct channel, a QR code, a branded app, or a telephone order, carries no platform commission. Developing direct ordering reduces the proportion of orders subject to commission economics.
Combo design for delivery profitability. Combos that pair lower food cost items like beverages and desserts with higher food cost proteins improve the blended food cost percentage of the delivery order above what the main dish alone would achieve.
Section 8: How to Set a Food Cost Target and Actually Hit It
A food cost target without a monitoring system is not a target. It is a wish.
How to set a realistic food cost target:
The right food cost target for any Indian restaurant is specific to its format, its price point, its cuisine type, and its channel mix. As a general reference:
Fine dining restaurants typically operate at 28 to 32% food cost because higher menu prices and premium ingredients coexist with higher service and ambience costs that the pricing supports.
Casual dining restaurants typically target 30 to 35% food cost.
QSR and fast food formats typically target 25 to 32% food cost because their menu prices are lower and portion control is more standardised.
Delivery-heavy operations should calculate their target against net revenue received rather than gross order value.
How to monitor food cost weekly rather than monthly:
The most important operational change a restaurant can make to food cost management is shifting from monthly food cost review to weekly food cost review. Monthly review discovers problems after 30 days of cost has already been incurred. Weekly review catches the same problems after 7 days.
Weekly food cost calculation requires weekly physical inventory counts of the highest-cost ingredients. This takes approximately 30 to 45 minutes and reveals the consumption pattern for the week against the revenue generated.
Section 9: How RetailPOS Dineazy Tracks and Controls Food Cost for Indian Restaurants
RetailPOS Dineazy provides the specific technology infrastructure that converts food cost management from a monthly accounting exercise into a daily operational practice.
Recipe management with gram-level ingredient mapping.
Every dish on the menu is configured in Dineazy with exact ingredient quantities at the gram or millilitre level. When supplier prices are updated in the system, the food cost percentage for every dish containing that ingredient updates automatically. The food cost dashboard shows the current cost percentage for every dish in real time without any manual calculation.
Automatic ingredient deduction from every sale.
Every order processed through Dineazy, from every channel, dine-in, Zomato, Swiggy, QR table order, or direct app order, automatically deducts the recipe-specified ingredient quantities from the live kitchen inventory. The kitchen management team can see current ingredient stock levels at any point during service without any manual stock check.
Daily wastage recording with reason codes.
Kitchen staff log every wastage event with the ingredient, quantity, and reason code directly in Dineazy. The daily wastage report shows total rupee value of waste at current ingredient prices. Monthly wastage reports identify patterns by ingredient, by category, and by reason code that enable targeted reduction.
Per-channel food cost reporting.
Dineazy reports food cost percentage separately for each ordering channel. Dine-in food cost, Zomato food cost after commission, Swiggy food cost after commission, and direct order food cost are each reported separately, giving the restaurant management team the accurate, channel-specific food cost data needed to make informed decisions about delivery pricing, menu curation, and direct ordering development.
Low stock alerts before service begins.
When any ingredient falls below its configured minimum level, Dineazy fires a low-stock alert to the kitchen manager before the service period begins. Stockouts during service that force menu 86ing, emergency purchases, or recipe substitutions are prevented because the alert fires early enough for a purchase order to be raised and fulfilled.
Multi-outlet food cost dashboard for chains.
For restaurant chains, the Cockpit dashboard shows food cost percentage for every outlet simultaneously. A chain owner who sees that one outlet is running at 43% food cost while others are at 35 to 37% can investigate the specific cause at that outlet immediately rather than discovering the discrepancy at month end.
Conclusion: Food Cost Creep Is Not Inevitable. It Is Invisible.
The Hyderabad restaurant owner from the opening of this guide did not make bad decisions in the eight months between a 33.2% food cost and a 41.3% food cost. He made the same decisions he had always made. He managed the kitchen the same way. He bought from the same suppliers. He kept the same menu prices.
What changed was that dozens of small, individually invisible cost pressures accumulated simultaneously: portion sizes drifted upward, a few supplier prices rose gradually, wastage increased slightly as the kitchen got busier, and delivery orders grew as a share of total volume without the food cost calculation adjusting for the commission impact.
None of these causes would have escaped notice if the right data had been visible at the right time. A dish-level food cost dashboard that updated in real time would have shown the portion creep within days of it beginning. A daily wastage report would have quantified the Rs 42,000 monthly cost of the kitchen’s increased wastage rate. A per-channel food cost report would have shown the delivery channel food cost climbing above 45% as delivery grew to 55% of orders.
The data that would have prevented Rs 1.15 lakh in monthly margin loss was already being generated by the restaurant’s own transactions. It simply was not being captured, organised, and presented in a way that made the problem visible before it became the August P&L.
Book a free demo and see how RetailPOS Dineazy gives your restaurant the dish-level food cost visibility to stop the drift. Visit retailpos.co.in/register-demo | Call 044-421 421 40 / 95660 44300 | Email salesenquiry@uniprotech.co.in
Frequently Asked Questions
Food cost percentage targets in Indian restaurants vary by format and price point. Fine dining restaurants typically target 28 to 32% because premium pricing supports both premium ingredients and higher service costs. Casual dining restaurants commonly operate at 30 to 35%. QSR and fast food formats target 25 to 32% due to standardised portion control and lower menu price points. Delivery-heavy restaurants should calculate their target against net revenue after platform commission rather than gross order value, which typically means the effective food cost target on delivery orders needs to be 5 to 10 percentage points lower than the dine-in target to maintain comparable margin after commission.
Weekly food cost review is the minimum standard for active food cost management. Monthly review discovers problems after 30 days of cost has already accumulated. Weekly review catches the same problems after 7 days, typically before the variance has become large enough to significantly affect the monthly result. Restaurants with recipe-linked inventory management systems like Dineazy can monitor food cost percentage daily from the dashboard, enabling even faster detection of any drift from the target.
The fastest single action that reduces food cost in most Indian restaurants is implementing gram-specific recipe standards for the five highest-volume dishes and enforcing them through kitchen training and portion measurement. Portion creep on high-volume dishes is the most common driver of food cost drift and is immediately controllable through recipe discipline. A 1 to 2 percentage point reduction in food cost percentage on the five highest-volume dishes typically produces a 0.5 to 1 percentage point improvement in overall restaurant food cost percentage within the first month of consistent implementation.
Platform commission affects food cost percentage because it reduces the net revenue per order without changing the ingredient cost. A dish with a 35% food cost at the menu price has an effective food cost of 45 to 50% when 28 to 30% commission is deducted from the revenue before calculating the ratio. Restaurants that calculate food cost percentage using gross order value including delivery orders at list price are systematically underestimating their true delivery channel food cost. The correct calculation uses net revenue received after commission in the denominator, which reveals the true margin performance of each delivery channel.
Yes. Dineazy supports sub-recipe management where shared preparation components like curry bases, marination mixtures, and sauce reductions are configured as sub-recipes with their own ingredient costs. When a dish uses a sub-recipe, its food cost calculation includes the cost of the sub-recipe's component ingredients at the appropriate quantity used in the dish, not a simplified flat cost for the prepared component. This ensures that food cost calculations for dishes with shared preparations accurately reflect the true ingredient cost even when multiple dishes draw from the same prepared component.
About RetailPOS
RetailPOS is an enterprise restaurant and retail POS solution by Unipro Tech Solutions Pvt Ltd, headquartered in Chennai, Tamil Nadu. With over 20 years of experience and 10,000 plus businesses served across India and globally, RetailPOS provides purpose-built restaurant management technology including Dineazy with recipe-level food cost management, automatic ingredient inventory deduction, daily wastage recording, per-channel profitability reporting, and the Cockpit multi-outlet dashboard for restaurant chains, QSR operators, and multi-outlet F&B groups across India.
Website: retailpos.co.in | Phone: 044-421 421 40 / 95660 44300 | Email: salesenquiry@uniprotech.co.in